A Closer Look at Credy ES: Services, Reputation, and Market Position

Discover Credy ES and take a closer look at its services, reputation, and position in the Spanish online lending market. Learn how Credy ES works, what loan options it offers, how its application process works, and what borrowers should consider before choosing an offer.
Table of Contents
What Is Credy ES?
Credy ES is an online financial marketplace focused on connecting consumers in Spain with short-term loan providers. Rather than functioning like a conventional bank that directly lends its own money, Credy describes itself as a loan broker and online loan search platform. Its website allows applicants to enter their requirements and personal information before being presented with loan options from participating providers. This distinction is important because the company itself says that the actual lending decision and loan conditions come from the individual lender, not Credy.
The wider Credy business dates back to 2013, when it was founded in Tallinn, Estonia. According to its corporate information, the company expanded internationally and operates across multiple countries and continents. Its Spanish operation focuses heavily on online consumer credit, particularly smaller loans designed for people who need relatively quick access to funds. The company’s current Spanish website promotes convenience, speed, online applications, and access to different lending partners.
Credy’s Business Model
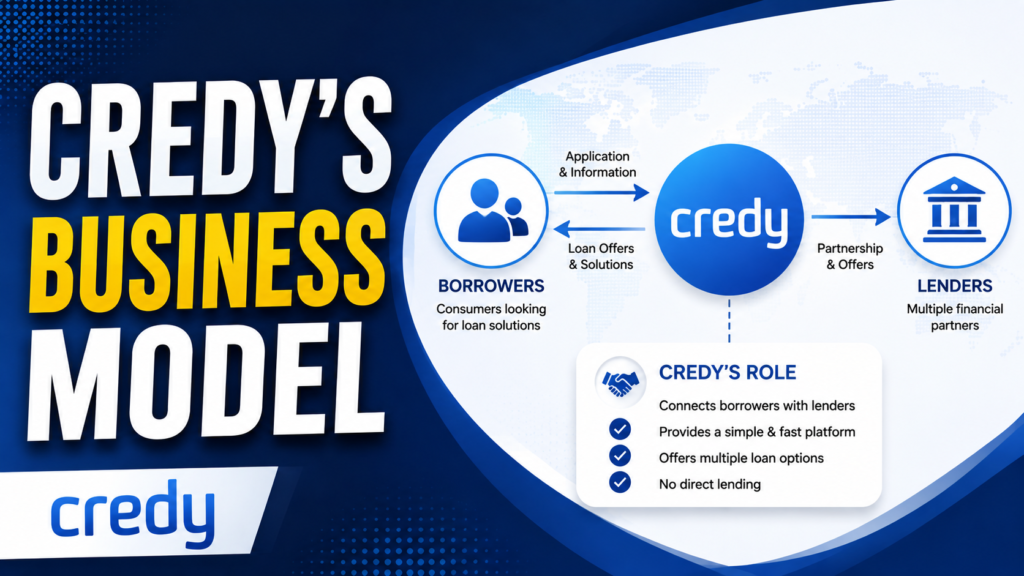
Credy’s business model is based around intermediation. The platform states that it does not determine whether an applicant receives financing and does not set the individual lender’s conditions. Instead, it acts as a bridge between consumers and participating financial companies. Credy’s FAQ also states that the company does not charge consumers for the mediation service.
This model can be useful when a borrower does not want to submit separate applications to multiple companies. The platform can simplify the initial search and potentially reduce the time required to find a suitable offer. Credy also markets itself toward consumers who may find traditional lending requirements difficult, including people seeking smaller amounts or applicants without conventional employment documentation.
However, the broker model creates an important responsibility for the customer. A Credy application does not automatically mean that Credy itself will provide the money. The final contract is generally with the lender whose offer the applicant accepts. That means customers should treat the Credy platform as the starting point of the borrowing process, rather than assuming that every advertised feature applies equally to every loan provider.
How Credy ES Works
The process is designed to be entirely online. Credy’s Spanish website explains that applicants select the amount they want and the repayment period, enter their information through an online form, and then review available loan options. Depending on the lender and circumstances, additional identity verification or information may be required.
The attraction is obvious. Someone facing an unexpected expense may not want to spend several days visiting financial institutions or preparing a large collection of documents. Credy presents its service as a faster alternative, with some pages stating that the application can be completed within minutes and that responses can arrive quickly. The platform also advertises 24/7 availability for its online service.
The important point is that application speed is not the same thing as guaranteed approval or guaranteed funding. The actual lender makes its own assessment. Even if a platform provides a quick response, the final offer can vary depending on the applicant’s circumstances and the lender’s criteria. Borrowers should therefore avoid making important financial decisions on the assumption that an advertised approval time means money is guaranteed.
Services Offered by Credy ES
Personal and Microloans
One of Credy’s main areas is small personal and microloans. These products are aimed at consumers who need relatively modest amounts of money for short-term financial needs. The Spanish site discusses situations such as unexpected bills, household expenses, urgent purchases, and other temporary liquidity problems.
Microloans differ from conventional personal loans because they are normally smaller and often have shorter repayment periods. That can make them useful for a specific short-term cash-flow problem, but it also means that the repayment schedule can be demanding.
A borrower should never judge a loan only by its small principal amount. The real question is how much must ultimately be repaid and whether that amount comfortably fits within the person’s budget.
Credy promotes flexibility by connecting applicants with different providers. This can make the platform attractive to people who want to compare several possibilities rather than immediately choose one lender. Still, the final financial product should be assessed on its own terms because the conditions can vary substantially between providers.
Fast Online Credit
Another major service category is fast online credit. Credy’s website markets quick applications for amounts that can help cover urgent expenses. Some pages advertise loans of up to €750, while the exact amount and repayment period depend on the specific product and lender.
The speed of this service is perhaps its strongest competitive advantage. Traditional financial services can involve account history, documentation, appointments, and formal approval processes. An online broker removes much of the physical friction from the initial application.
That convenience, however, should not encourage rushed borrowing. Fast access to money can be useful when a genuine emergency occurs, but it can also make it easier to accept an expensive loan without carefully reviewing the agreement. The best use of an online credit marketplace is therefore not simply to find the fastest offer but to find an offer whose total cost and repayment requirements make sense.
The Online Loan Application Process
The typical Credy process can be summarized in a few stages:
- Select the amount and repayment period.
- Enter the requested personal information.
- Submit the application.
- Review available offers from participating lenders.
- Examine the lender’s terms and costs.
- Accept an offer only after understanding the repayment obligation.
Credy’s own materials describe the process as online and emphasize simplicity and speed. Some Spanish pages advertise amounts such as €50 to €750, while other Credy-related information presents broader ranges depending on the specific product or provider. This variation reinforces an important lesson: the exact amount, term, cost, and eligibility criteria should be checked on the individual offer rather than assumed from a general marketing page.
Credy ES Eligibility and Requirements
Credy’s Spanish website states that applicants generally need to be 18 or older, legally resident in Spain, and have identification, an active telephone number, an email address, and a Spanish bank account in their name. Individual lenders may request additional verification depending on the circumstances.
One of the platform’s recurring marketing themes is accessibility. Credy promotes options that may be available without a traditional payslip or guarantor and discusses applications from consumers who may have difficulties obtaining conventional bank financing.
That does not mean everyone will be approved. Each lender remains responsible for evaluating applications and setting its own criteria. A customer should therefore distinguish between eligibility to submit an application and eligibility to receive a particular loan.
This is especially important for borrowers with limited income or existing debt. A loan may be technically available while still being financially unsuitable. The ability to obtain credit should never be confused with the ability to comfortably repay it.
Credy ES Pricing and Loan Terms
Loan pricing is one of the areas that deserves the closest attention. Credy acts as an intermediary, meaning the exact cost is determined by the lender making the offer. Credy’s own materials indicate that the expenses associated with an offer are presented through the relevant loan’s terms and TAE, or Tasa Anual Equivalente.
Some promotional pages also advertise a first loan at 0% interest for qualifying new customers, depending on the lender and offer. This should not be interpreted as a universal condition for every applicant. Promotional financing normally has specific eligibility requirements, limits, and repayment conditions, so the actual agreement should always be checked before accepting.
Factor | What to Check |
Loan amount | Exact amount being offered |
Repayment period | Number of days or installments |
TAE | Overall annualized cost indicator |
Fees | Any administration or other charges |
Total repayment | Amount you will actually return |
Promotional rate | Whether special conditions apply |
Late-payment terms | Charges or consequences after missed payments |
Lender | The company actually providing the money |
Who May Benefit From Credy ES?
Credy may be particularly useful for consumers who need a relatively small amount of money and prefer an entirely online application. It can also appeal to people who want to explore several lending possibilities rather than approaching lenders individually.
Its model may be convenient when time matters. Someone facing a short-term cash-flow problem may value a platform that can quickly connect them with potential lenders. The service can also be useful for people who find conventional bank lending requirements difficult, although availability always depends on the lender’s criteria.
The important condition is financial discipline. A fast loan is most useful when the borrower already knows how and when the money will be repaid. Without that plan, convenience can become a liability.
Reputation and Customer Experience
Credy’s reputation is more complicated than simply labeling it “good” or “bad.” The company has a substantial international presence and says it operates across numerous markets, while its Spanish website continues to promote its brokerage and loan-search services. Its corporate website currently claims operations in 18 countries across three continents and more than one million satisfied customers, although these are company-reported figures rather than independently audited market statistics.
At the same time, online review evidence can be mixed and sometimes relates to similarly named Credy domains or services. For example, a Trustpilot page for credy.in, rather than the Spanish Credy.es service, currently shows a 2.0/5 score from 11 reviews. Because this is a different domain, those reviews should not automatically be treated as evidence about Credy ES.
Positive Aspects
Credy’s strongest customer-facing advantages are convenience, speed, and the ability to explore different lending options through one platform. The company emphasizes a simple online application, assistance throughout the process, and access to multiple providers.
For consumers who dislike traditional paperwork, this can be a meaningful advantage. The platform effectively turns the initial loan search into an online shopping-style experience: enter your needs, receive potential options, and compare them before deciding. That model is particularly suited to a digital-first audience.
Another positive is that Credy clearly identifies itself as a broker rather than the direct lender in its Spanish materials. This distinction helps customers understand where the final financing decision comes from.
Concerns and Potential Drawbacks
The biggest concern is not necessarily the platform itself but the nature of short-term borrowing. Small loans can become expensive when repayment periods are short or when fees and interest accumulate. A product that solves today’s cash shortage can create another problem next month if repayment is not properly planned.
Another issue is that the marketing language can make the process sound extremely simple. Words such as “fast,” “easy,” and “without paperwork” are attractive, but financial products deserve more scrutiny than ordinary online purchases. The customer needs to understand who the lender is, what the TAE is, what the total repayment will be, and what happens if payment is late.
The broker structure also means that the user should not assume every offer is identical. Credy may facilitate the connection, but the lender controls the actual financial contract. That makes reading the final terms essential.
Also Read
Key Benefits of Using Semantix for Data-Driven Business Decisions
Upgrade Your Restaurant or Home Setup With Vevor Kitchen Solutions
The Future of Online Events and Marketing With LiveWebinar INT
Why Fashion Shoppers Are Exploring Milanoo.com for Unique Styles
How Aporro Can Help You Find Products That Match Your Lifestyle
Credy’s Position in the Spanish Market
Credy occupies a niche within Spain’s broader online consumer-credit and financial comparison market. Its proposition is based less on competing with banks as a direct lender and more on simplifying access to alternative lending providers.
The company positions itself as a marketplace connecting borrowers and lenders. Its Spanish website describes a network of providers and emphasizes the ability to compare or receive different loan possibilities through the platform.
This is a competitive position because consumers increasingly expect financial services to work like other digital services: quickly, remotely, and with fewer physical barriers. Credy’s online-first model fits that expectation.
At the same time, its market position has a natural limitation. Traditional banks may provide broader financial products, longer-term lending, current accounts, mortgages, savings services, and established customer relationships. Credy is much more specialized around online consumer-credit discovery and short-term financing.
Is Credy ES a Lender or a Broker?
This is one of the most important questions to answer.
Credy ES operates as a broker/intermediary rather than simply being the lender behind every loan. Its Spanish FAQ describes Credy as an internet-based search service for fast loans and explains that applications can result in options from different loan providers.
That means the customer’s relationship ultimately depends on the provider whose offer is accepted. Credy can facilitate the search, but it does not necessarily provide the capital itself.
This model has both advantages and disadvantages. The advantage is convenience: one application can potentially open access to multiple possibilities. The disadvantage is that the borrower must pay close attention to the identity and conditions of the actual lender.
Who Should Consider Other Options?
Credy may not be the best choice for every financial situation. Consumers who need a large loan over several years should compare conventional personal-loan products, where longer repayment structures may be more appropriate.
It may also make sense to consider alternatives if the proposed TAE or total repayment cost is too high. Depending on the situation, alternatives could include negotiating a payment plan with a service provider, using existing savings, comparing bank credit, or postponing a non-essential purchase.
The key principle is simple: don’t borrow simply because borrowing is available. Credit should solve a manageable financial need, not become the default response to recurring budget problems.
How to Evaluate a Credy Loan Offer
A sensible evaluation starts with the final offer rather than the advertisement. Look at the exact lender, amount, repayment period, TAE, fees, and total amount payable.
Then ask yourself whether the repayment fits comfortably into your budget. If repayment would require another loan, a credit-card balance, or skipping essential expenses, the offer is probably not appropriate.
A useful checklist is:
- Who is the actual lender?
- How much will I receive?
- How much will I repay in total?
- What is the TAE?
- What fees apply?
- When is repayment due?
- What happens if I pay late?
- Is the promotional rate conditional?
- Can I comfortably repay without borrowing again?
These questions turn an emotionally driven borrowing decision into a practical financial comparison.
Conclusion
Credy ES represents the growing shift toward digital consumer finance in Spain. Instead of acting like a traditional bank, it provides an online route through which consumers can search for and potentially receive offers from participating lenders. Its emphasis on speed, convenience, online applications, and smaller loans gives it a distinct place within the alternative lending marketplace.
The platform can be useful when someone needs a relatively small amount of money and wants to compare online financing options quickly. But speed should never replace careful financial evaluation. The most important step is to look beyond the headline offer and understand the lender, TAE, fees, repayment period, and total amount that will eventually leave your bank account.
Frequently Asked Questions
No. Credy ES presents itself as an online loan broker and search platform, connecting applicants with participating loan providers rather than operating simply as a conventional bank.
Credy states that it acts as an intermediary. The participating lender makes the final financing decision and determines the specific conditions of the loan.
The Spanish platform primarily promotes online personal loans, microloans, and fast consumer credit, with advertised amounts and repayment periods varying by product and lender.
Some Credy pages advertise a first loan at 0% interest, but this depends on the specific lender, offer, and eligibility requirements. Customers should verify the exact promotional conditions before accepting an offer.
Check the actual lender, TAE, fees, repayment period, total repayment amount, late-payment conditions, and any promotional requirements. These details are more important than simply choosing the fastest available offer.
Table of Contents
Popular Posts

-
 Affordable Technical SEO Audit for Small Business: A Complete Guide26 Jun 2025 Blog
-
 How to Get an Affordable Technical SEO Audit for Small Business27 Jun 2025 Blog
-
 The Ultimate Local SEO Audit Checklist for Startups28 Jun 2025 Blog
-
 Local SEO Audit Checklist for Startups: A Beginner’s Guide28 Jun 2025 Blog
-
 Top On-Page SEO Audit Steps for Service Websites Every Business Should Know29 Jun 2025 Blog
-
 The Impact of On-Page SEO Audit Steps for Service Websites on UX01 Jul 2025 Blog
-
 Technical SEO for WordPress: The Ultimate Beginner’s Guide01 Jul 2025 Blog
-
 Technical Mobile SEO Audit Tips for Developers02 Jul 2025 Blog
Related Post